Gesamtzahl der Seitenaufrufe

Mittwoch, 13. März 2013

Grenada 25: EMTA is recommending that flat trading commence on March 13, 2013


As you may be aware, Grenada announced on March 8, 2013 that it will begin discussions with its creditors regarding a restructuring of its public debt, and confirmed that it will not have the resources to pay the interest payments on its 2025 bonds due on March 15 (nor does it expect to have the funds to do so within the relevant grace period). EMTA Members may access the full text of the Press Release by Clicking Here; or you may copy and paste the following link into your internet browser:http://www.emta.org/WorkArea/linkit.aspx?LinkIdentifier=id&ItemID=7948
Accordingly, after consultations with major market participants, EMTA is recommending that flat trading commence on March 13, 2013 (unless otherwise agreed). EMTA Members may access the full text of the Market Practice recommendation by Clicking Here;or you may copy and paste the following link into your internet browser: http://www.emta.org/WorkArea/linkit.aspx?LinkIdentifier=id&ItemID=7952
EMTA offers a wide range of Emerging Markets information. Please see our website at: http://www.emta.org


This e-mail was sent from EMTA, Trade Association For The Emerging Markets (eramirez@emta.org) to rolfjkoch@web.de.

Ranking des Grenada 12 // sanfte pari passu clause ?


Ranking
The notes will be general, direct, unconditional, unsubordinated and unsecured obligations of the
Government and will be backed by the full faith and credit of the Government. The notes will be Public
External Debt of the Government. The notes will rank equally among themselves and with all other
existing and future unsubordinated and unsecured Public External Debt of the Government.

Dienstag, 12. März 2013

Grenada 9.375 Grena12 Nts-S USP48863AA55 // ein pari passu play in New York ?


Guten Morgen Herr Koch
Gemäss Bondhandel stellt JP Morgen für eine Million USD folgende Preise; Bid 31 / Ask 54 (indikativ)
Bitte teilen Sie mir mit, ob ich einen Kaufauftrag im Markt platzieren soll.
Danke und einen guten Tag.
Freundliche Grüsse


ISIN:USP48863AA55
NSIN:AT: 860920
CH: 1442330
Common: 015049251
DE: 860920
GB: 2962551
US: P48863AA5

Montag, 11. März 2013

Belize....schon wieder ein swap mit Einbussen...


PRESS RELEASE FOR IMMEDIATE RELEASE
March 8, 2013
Belize Debt Exchange Offer Successful
Belmopan, Belize: The Government of Belize announced
today that holders of 86.17 percent of the country's U.S. Dollar Bonds due
2029 (the “2029 Bonds”) had tendered their bonds in response to Belize's
February 15, 2013 offer to exchange those instruments for new Belize U.S.
Dollar Bonds due 2038 (the “2038 Bonds”). Belize's offer required tenders
to be submitted to Citibank, in its capacity as the Exchange Agent for the
transaction, by 5:00pm (New York time) today.
Under the terms of the 2029 Bonds and Belize's exchange
offer, holders of not less than 75 percent of the 2029 Bonds have instructed
the Trustee for those instruments to tender the entirety of the 2029 Bonds in
exchange for 2038 Bonds in accordance with the terms of Belize's offer.
The results of the tender process that ended today means that such an
exchange of the entirety of the 2029 Bonds is expected to take place at a
closing of the transaction later this month.
* * * *
Questions regarding this press release may be directed to
Joseph Waight, Financial Secretary (+501 822 0367);
(financial.secretary@mof.gov.bz)

Grenada Bond.....ca 54 % nur noch 6 Mio ausstehend


Werter Herr Koch

Der Handel kann nur indikativ einen Kaufkurs von 54 geben, ob die Menge von 100‘000 verfügbar wäre, ist unsicher, da nur noch 6 Mio. ausstehend sind.

Ich hoffe, Ihnen damit dienen zu können und verbleibe mit freundlichen Grüssen

Sonntag, 10. März 2013

Handelseinstellung: USP48863AA55 Grenada, Government of... Grenada 16.02.2011 7823


Bekanntmachung Freiverkehr (Open Market)
Einstellung Anleihen
Kündigung der Einbeziehung und Einstellung der Preisfeststellung:
Nr. ISIN Börsen-
kürzel
Name Land Letzter
Handelstag
Skontro
1. XS0542650188 AIB Mortgage Bank Irland 16.02.2011 7637
2. CH0124138790 Pfandbriefbank schweizerischer
Hypothekarinstitute
Schweiz 16.02.2011 7812
3. USP1330HAZ75 Banco Hipotecario S.A. Argentinien 16.02.2011 7823
4. XS0074563015 Buenos Aires, City of... Argentinien 16.02.2011 7823
5. USP48863AA55 Grenada, Government of... Grenada 16.02.2011 7823
6. USG9191BFV56 Unibanco - União de Bancos Brasileiros
S.A.
Brasilien 16.02.2011 7823
7. DE000NLB5ME3 Norddeutsche Landesbank Girozentrale Deutschland 16.02.2011 8710
8. DE000A1AZUQ7 Citigroup Funding Inc. USA 16.02.2011 8732
Frankfurt am Main, 16.02.2011
Deutsche Börse AG
Sollten Sie noch Fragen haben, wenden Sie sich bitte an:
If there are any questions, please contact:
Listing & Issuer Services 069 211 13555
Market Supervision 069 211 11050

http://deutsche-boerse.com/INTERNET/IP/ip_beka.nsf/0/89C403E12957F57DC125783900505AEB/$File/Einstellung_Anleihen_FV_20110216.pdf?OpenElement

Donnerstag, 7. März 2013

Government of Grenada:2005-15.9.25 Reg S Step Up (UNSUBORDINATED)

Grenada 25 SU Reg S (DUS) - 15.09.2025  Price: 48 USD Chg. (in%): ±0 USD (±0.00%) Volume: -
Bonds:Government of Grenada:2005-15.9.25 Reg S Step Up (UNSUBORDINATED)
Symbol: Type:Floating Rate NoteIndustry:Länder/Zentralregierungen
Valor:2282281Domicile:GrenadaExchange:Boerse Dusseldorf AG

Klage Im-Ex-Bank-China v Grenada
http://ftalphaville.ft.com/files/2013/03/13cv014501.pdf


Pari passu, the cross-sovereign contamination

Some excerpts from a lawsuit filed by the Export-Import Bank of China (Taipei) against Grenada in a United States district court on March 4, 2013…
If you have been following the pari passu saga on ratable payment of sovereign debt — they tell their own story. (Click to enlarge all images.)
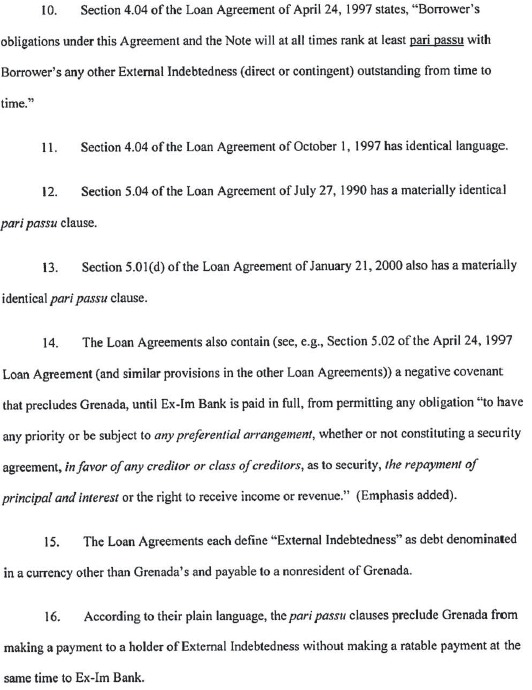
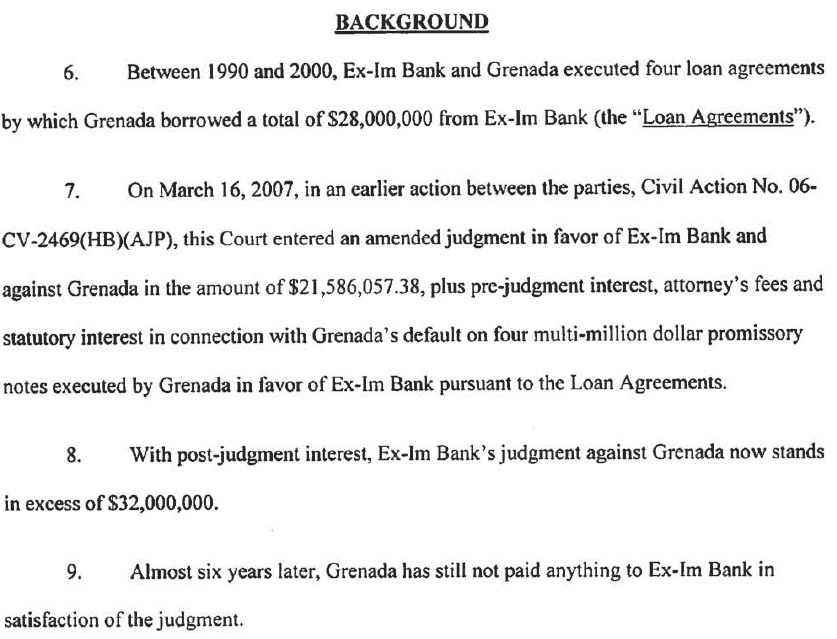
1.) Ex-Im Bank already has a judgement on $32m of debt defaulted on by Grenada.
2.) The loan debt had a pari passu clause, and negative pledge language.
3.) Let’s just spell that last bit out, as cited by Ex-Im Bank.
According to their plain language, the pari passu clauses preclude Grenada from making a ratable payment to a holder of External Indebtedness without making a ratable payment at the same time to Ex-Im Bank.
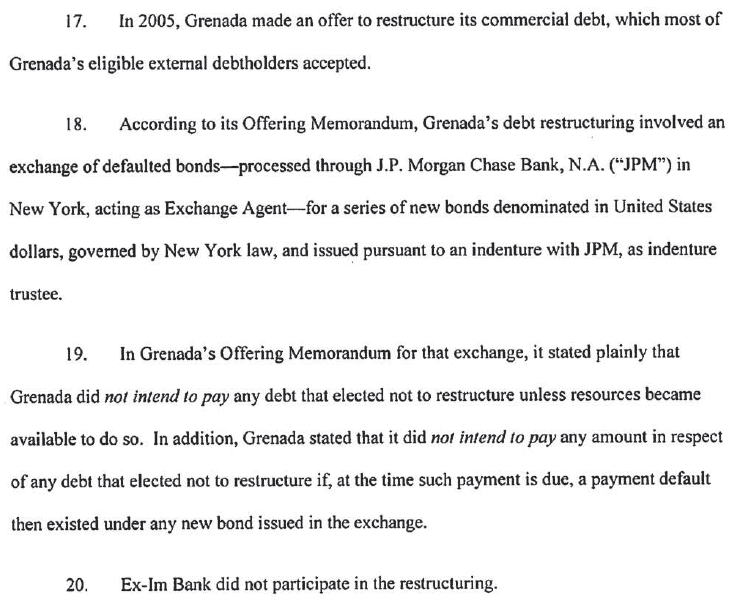
4.) Ex-Im Bank stayed out of Grenada’s 2005 debt restructuring.
5.) It has been watching Grenada pay the people who did restructure.
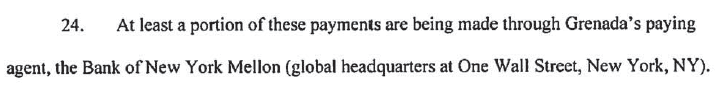
6.) Bank of New York handled some of that dough. Bank of New York lives in New York.
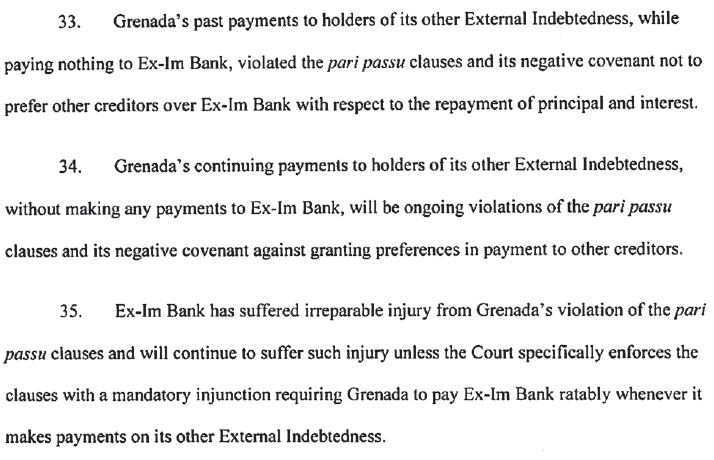
7.) Ex-Im Bank is now coming after these payments to Grenada’s restructured bondholders. (Hello, intercreditor consequences of ratable payment.)
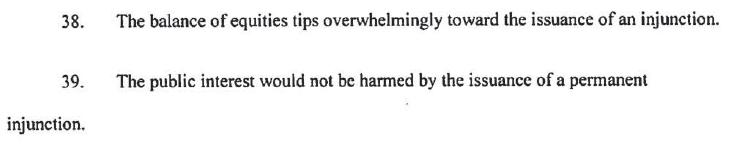
8.) And Ex-Im Bank’s citing equity.
They didn’t even wait for a final Second Circuit ruling on Argentina making ratable payments to its holdouts. (Why should they, actually? The implications of ratable payment are arguably clear.)
Incidentally observe point 1) there, that Ex-Im Bank is exploring this avenue having already won judgement against Grenada. (The story of their dispute is a long one.)
The $1.3bn of claims involved in NML’s pari passu litigation against Argentina were not judgement debts. Nevertheless. EM Ltd, which holds a prior judgement against Argentina, said (in a pro-holdout amicus brief) that while “the District Court has not yet been asked to address whether the Equal Treatment Provision can be used to enforce an existing judgment,” EM Ltd “believes that the Equal Treatment Provision applies with identical force in the post-judgment context”.
And now we have crossed into new territory.
Post your own comment
User8095217Update your profile
Subscribe to comments
Comments
Sorted by oldest first | Sort by newest first
  1. Reportplasmaj | March 6 6:46pm | Permalink
    Except when they got their judgment they gave up their rights with respect to the bonds, including pari passu. Citi had a good piece explaining that.
  2. ReportJorge Marquez | March 6 7:31pm | Permalink
    Can you link that plasmaj? Or, at least, elaborate on what you just said. I'm intrigued...
  3. Reportanoldbanker | March 7 2:36pm | Permalink
    Argentina's equal treatment clause applies to payments; Grenada's only applies to ranking of the different debts. This is a critical distinction thoroughly discussed in academic analyses of pari passu.
  4. ReportJoseph Cotterill, FT | March 7 5:20pm | Permalink
    anoldbanker & plasmaj - Yep. Sure, it's not a particularly cast-iron case in itself (I think) because of the judgement issue and the lack of payments language. But it is striking and a sign of an important change that they thought they can even try.